
Structural figures reveal the scale of the French imbalance. Ski lift operators generate on average 95% of their revenue in winter, sporting goods stores 85%, and hoteliers 75% (1).
The ski domain accounts for around €2 billion in revenue, within a resort economy that exceeds €10–12 billion across all activities (2).
This concentration directly impacts the cost structure. The fixed costs of a ski lift operator hover around 49% of annual turnover, including safety-related obligations, and investment absorbs each year a quarter of receipts (3).
The productive apparatus remains immobilized while depreciation runs. Each additional week of operation improves the return on capital, provided it covers the variable costs it generates. The entire question hinges on this threshold.
The ski domain accounts for around €2 billion in revenue, within a resort economy that exceeds €10–12 billion across all activities (2).
This concentration directly impacts the cost structure. The fixed costs of a ski lift operator hover around 49% of annual turnover, including safety-related obligations, and investment absorbs each year a quarter of receipts (3).
The productive apparatus remains immobilized while depreciation runs. Each additional week of operation improves the return on capital, provided it covers the variable costs it generates. The entire question hinges on this threshold.
Tyrol and South Tyrol Have Already Made the Journey
In Austria, 28.1% of the 2025 overnight stays occurred in April, May, September, October, and November; in Tyrol, October overnight stays gained about a quarter over ten years (4).
October 2025 accounts for 2.35 million overnight stays, one tenth of the summer season (5). In the 2024/2025 tourist year, Tyrol logged 49.6 million overnight stays, split 53% winter and 47% summer (6): the seasonal balance exists across a region with 340,000 beds.
The South Tyrol delivers the most striking signal: in 2025, October recorded more arrivals than January, 695,000 vs 691,000 (7).
The fifth season, the Törggelen, the new wine and chestnuts, reaches the size of a winter month. The neighboring Trentino shows in September 2026 Italy’s first saturation rate on booking platforms (8).
Serfaus-Fiss-Ladis sums up the trajectory: 100% more summer overnight stays since 2005, versus 25% in winter, with the value-added ratio remaining 60 to 40 in favor of winter (9). Volume shifts faster than value, and the project spans decades.
October 2025 accounts for 2.35 million overnight stays, one tenth of the summer season (5). In the 2024/2025 tourist year, Tyrol logged 49.6 million overnight stays, split 53% winter and 47% summer (6): the seasonal balance exists across a region with 340,000 beds.
The South Tyrol delivers the most striking signal: in 2025, October recorded more arrivals than January, 695,000 vs 691,000 (7).
The fifth season, the Törggelen, the new wine and chestnuts, reaches the size of a winter month. The neighboring Trentino shows in September 2026 Italy’s first saturation rate on booking platforms (8).
Serfaus-Fiss-Ladis sums up the trajectory: 100% more summer overnight stays since 2005, versus 25% in winter, with the value-added ratio remaining 60 to 40 in favor of winter (9). Volume shifts faster than value, and the project spans decades.
Four Levers, Uneven Maturities
Business tourism leads the way with its suitability for the off-season: in 2023, it already accounted for 10% of the overnight stays in the two Savoie regions (10). September and October correspond to the peak of back-to-work seminars, precisely when beds free up, and the economic profile fits perfectly: high per-capita spending, bundled volume, advanced bookings, weather-insensitive demand.
Three conditions drive success: a coherent plenary capacity aligned with hotel capacity, clear rail accessibility, and a single commercial contact.
Sporting events, from trail running to ultra-cycling, structure the calendar and bring guests who willingly extend their stay.
Gastronomy and agricultural supply chains remain the most underexploited lever in France, while the South Tyrolean Törggelen shows that a rural tradition can become a commercial season.
Wellness and gentle mountains attract couples and seniors outside school holidays. The refuges confirm demand: the FFCAM gains 30% in June, September and October (11).
Three conditions drive success: a coherent plenary capacity aligned with hotel capacity, clear rail accessibility, and a single commercial contact.
Sporting events, from trail running to ultra-cycling, structure the calendar and bring guests who willingly extend their stay.
Gastronomy and agricultural supply chains remain the most underexploited lever in France, while the South Tyrolean Törggelen shows that a rural tradition can become a commercial season.
Wellness and gentle mountains attract couples and seniors outside school holidays. The refuges confirm demand: the FFCAM gains 30% in June, September and October (11).
Conditions for a Profitable Opening
Opening in the off-season is a calculation more than an intention. Four principles emerge from successful Alpine models.
Open one facility rather than an entire domain first: a single structuring lift, sized for pedestrians and mountain biking, reaches its threshold long before a full area does.
Then contract the opening with hoteliers, restaurateurs and shops, because a lift operating in front of closed venues leads to disappointment and costs.
Aim for value over volume, especially. In Tyrol, the vacationer spends on average €223 per day in winter and €176 in summer (12): the off-season pays off through the average spend, longer stays, and the business segment, rather than through occupancy.
Finally, mutualize at the valley level, where 2,000 open beds weigh more than 500 isolated beds, and where recruitment becomes solvable.
Open one facility rather than an entire domain first: a single structuring lift, sized for pedestrians and mountain biking, reaches its threshold long before a full area does.
Then contract the opening with hoteliers, restaurateurs and shops, because a lift operating in front of closed venues leads to disappointment and costs.
Aim for value over volume, especially. In Tyrol, the vacationer spends on average €223 per day in winter and €176 in summer (12): the off-season pays off through the average spend, longer stays, and the business segment, rather than through occupancy.
Finally, mutualize at the valley level, where 2,000 open beds weigh more than 500 isolated beds, and where recruitment becomes solvable.
The ESG Aspect, Quantified
Lengthening the seasons yields measurable social effects. Seasonal jobs account for 14% of the annual salaried employment in mountain basins and exceed 20% during peaks; 19,300 people held seasonal work across a full year in the studied basins (13).
Nearly four in ten combine their season with a job located more than 50 kilometers away (14). Two short seasons force forced mobility, which contracts from April to October then December to March into an annualized path. Housing remains a constraint: 3% of seasonal workers have employer-provided housing (15).
On carbon, the arithmetic favors the off-season. Transport accounts for 52% of a day’s emissions in a resort according to the Utopies study for ADEME, versus about 3% for the ski area’s operation (16); a prior ANMSM report placed it at 57% (17).
The ratio improves in two ways in autumn: longer stays spread travel over more overnight stays, and a business or urban clientele is far more willing to use the train than February’s family clientele. On water, finally, the off-season taps into the resource when it is reconstituting, contrary to the August peak that the law of 18 August 2026 now invites to manage as a shared use (18).
Nearly four in ten combine their season with a job located more than 50 kilometers away (14). Two short seasons force forced mobility, which contracts from April to October then December to March into an annualized path. Housing remains a constraint: 3% of seasonal workers have employer-provided housing (15).
On carbon, the arithmetic favors the off-season. Transport accounts for 52% of a day’s emissions in a resort according to the Utopies study for ADEME, versus about 3% for the ski area’s operation (16); a prior ANMSM report placed it at 57% (17).
The ratio improves in two ways in autumn: longer stays spread travel over more overnight stays, and a business or urban clientele is far more willing to use the train than February’s family clientele. On water, finally, the off-season taps into the resource when it is reconstituting, contrary to the August peak that the law of 18 August 2026 now invites to manage as a shared use (18).
Sources
A propos d’Armelle Solelhac
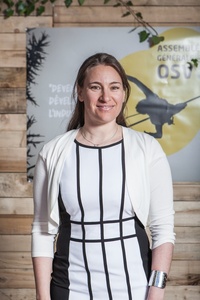
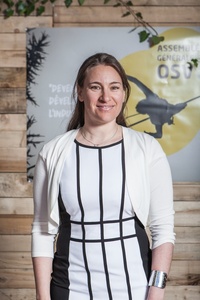
Graduated with a Master’s in Law and from ESCP Business School, Armelle Solelhac set out in 2005 to travel the world across 286 ski resorts in 27 countries on 5 continents over 2 years.
Upon her return, she founded SWiTCH, a marketing strategy and CSR consultancy specialized in tourism and outdoor sports.
En 2016, she embarked on a second world tour of more than 100 coastal destinations in 14 countries across 4 continents.
In October 2019, she published a work that has become a reference on the Management and Marketing of Mountain Resorts Worldwide.
Upon her return, she founded SWiTCH, a marketing strategy and CSR consultancy specialized in tourism and outdoor sports.
En 2016, she embarked on a second world tour of more than 100 coastal destinations in 14 countries across 4 continents.
In October 2019, she published a work that has become a reference on the Management and Marketing of Mountain Resorts Worldwide.