
In September 2026, departures continued to trend downward. The number of bookings fell by 5.5% compared to September 2025. However, the decline is less pronounced than in August, when it reached 9%.
The business volume associated with departures decreased by 4.1%, while the average basket rose by 1.5%, to €1,853. This increase is therefore not enough to offset the drop in the number of bookings. The Observatory therefore concludes that September activity remains subdued and does not yet indicate a change in trend.
The trends vary by region. Long-haul travel is the most penalized, with a 14.6% drop in bookings. Mid-haul fares better, with a decline limited to 2.8%. France, for its part, shows a 9.1% drop in bookings.
Departures remain below September 2025: business volume -4.1%, bookings -5.5%, average basket up +1.5% to €1,853. The drop in bookings is less pronounced than in August (-9%).
Mid-haul
Long-haul
Business volume advances (+3.3%) despite a slight drop in bookings (-1.7%), driven by a rise in the average basket (+5.1% to €2,004). The average lead time between booking and departure reaches 74 days, up 6% year over year. The mid-haul segment is the only zone posting growth in bookings (+7.1%).
Mid-haul
Long-haul
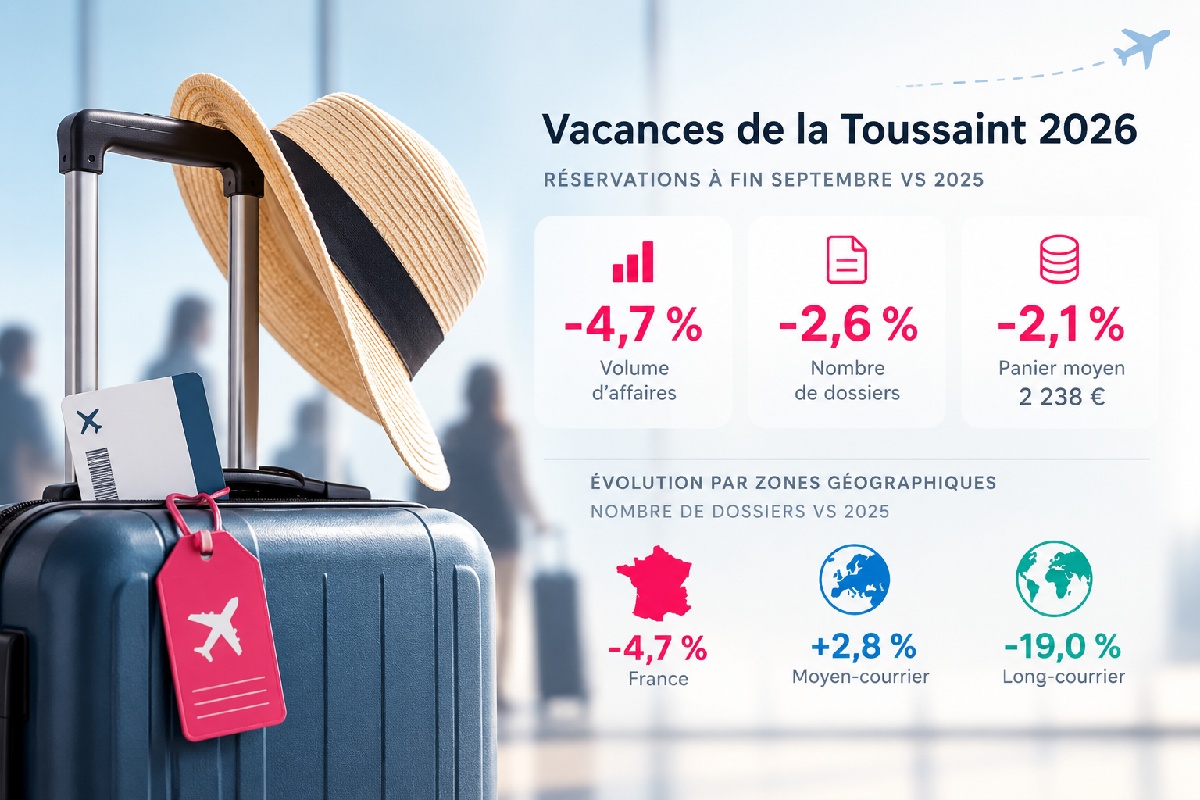
As of the end of September, reservations for departures between October 17 and November 2, 2026 remain below 2025: business volume -4.7%, bookings -2.6%, average basket -2.1% at €2,238. Long-haul shows the steepest decline (-19.0% in bookings); mid-haul is the only zone in growth (+2.8%).
Mid-haul
Long-haul
Departures & reservations in September: 01/09 – 29/09/2026 · All Saints’ Day: reservations 01/01 – 29/09/2026, departures 17/10 – 02/11/2026.
Data drawn from travel agencies using the Orchestra platform (20+ brands, 2 years minimum).
‘;
Orchestra and Sabre Strengthen Airline Distribution Partnership

This development aimed to broaden Orchestra’s air distribution capabilities and to bring more flexibility to travel professionals in managing their content and bookings.
Through the integration of Sabre within Orchestra and the Travelsoft Transport Hub, professionals could access different types of air content via a unified API.
The solution aggregated offers from traditional carriers via EDIFACT, those from low-cost carriers (LCC), and content using the NDC standard.
Distribution parameters could also be adapted to the business models and commercial strategies of each actor.
Automated After-Sales Management
This automation was intended to allow agency and tour-operator teams to reduce the time spent processing cases and to gain operational efficiency.
Sabre also highlighted its Multi-tickets feature, designed to facilitate the construction of itineraries that combine multiple tickets.
The contents and features stemming from this collaboration were notably accessible within Orchestra and Travel Compositor, strengthening their integration into the Travelsoft ecosystem.
 Published by Amelia Brille TourMaG.com Editor
See all articles by Amelia Brille


EDV Barometer: Orchestra Reservations Rebound in August, but Summer 2026 Remains Lagging
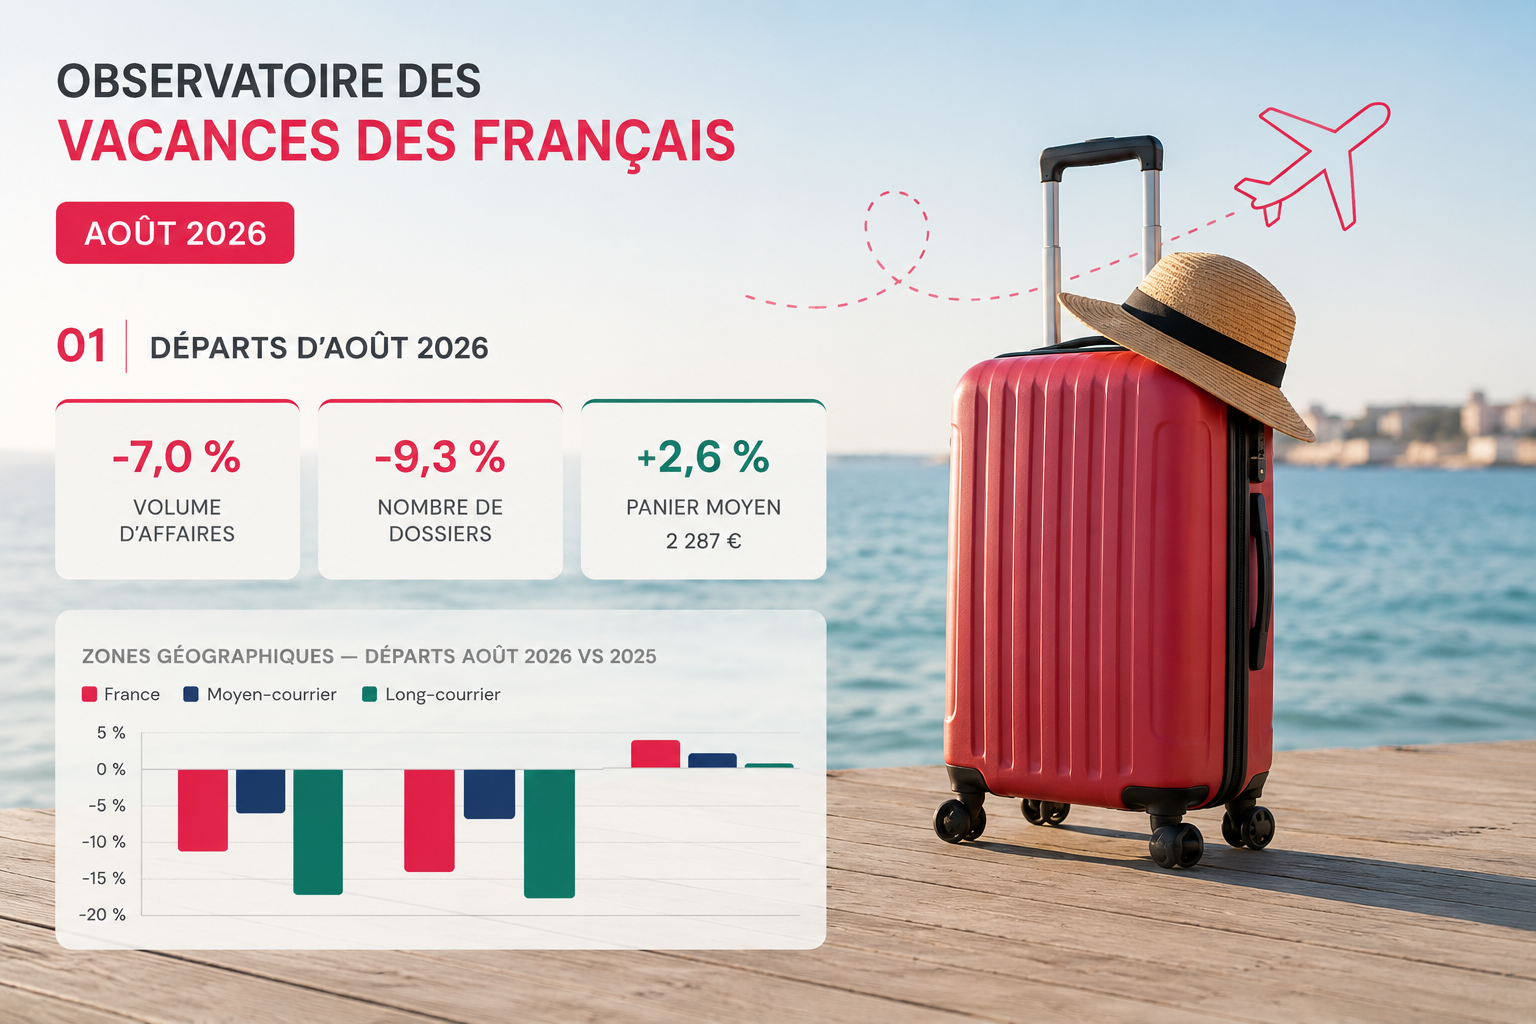
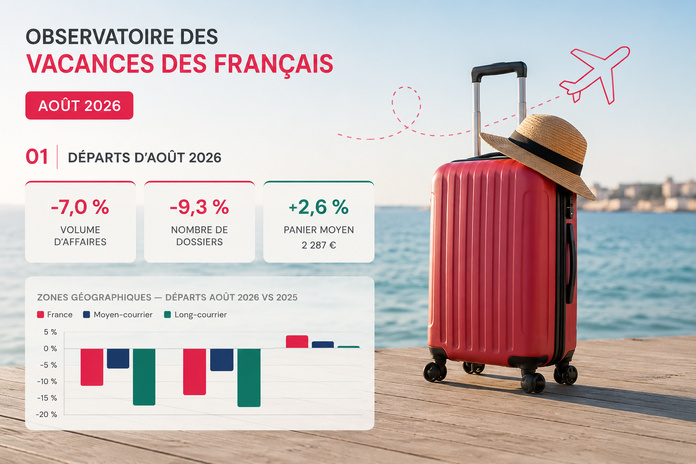

According to the new Observatory of French Holidays EDV-Orchestra, departures recorded from August 1 to 26 show a 9.3% drop in the number of bookings and a 7% decline in business volume compared with August 2025. The rise in the average basket, from 2.6% to €2,287, only softens the decline.
However, the data reveal a positive signal: bookings made in August are rising again.
In August 2026, the number of bookings grows by 2.9% year on year while the business volume leaps by 7.6%. The average basket reaches €1,697, up 4.6%.
The average booking lead time indeed stands at 55 days, i.e., two days longer than in 2025. More importantly, the share of bookings made less than 30 days before departure drops to 46.2%, compared with 49.7% a year earlier. Conversely, bookings made more than 90 days in advance rise slightly, to 18.9% versus 18% in 2025.
The recovery in sales thus does not signal a mass shift to last-minute bookings, but rather a slight reintroduction of forward planning in booking behaviors, explains the barometer.
The infographic: numbers at a glance
Confirmed slowdown compared to August 2025: business volume -7.0%, bookings -9.3%, average basket up (+2.6%) to €2,287. The rise in the basket does not offset the decline in volumes; the summer season remains downward oriented. Long-haul remains the most affected segment (-16.1% in bookings).
Medium-haul
Long-haul
Recovery in the trend after several months of decline: the business volume returns to positive (+7.6%), supported by a rise in bookings (+2.9%) and in the average basket (+4.6% to €1,697). The average booking lead time is 55 days, two days longer than in 2025.
Medium-haul
Long-haul
To date, reservations for September 2026 departures remain below 2025: business volume -5.4%, bookings -5.8%, average basket almost stable (+0.4% at €1,959). Long-haul concentrates the sharpest decline (-16.6% in bookings).
Medium-haul
Long-haul
Departures & reservations August: 01/08 – 26/08/2026 · September: reservations 01/01 – 26/08/2026, departures 01/09 – 30/09/2026.
Data from travel agencies using the Orchestra platform (20+ brands, at least 2 years).
‘;
}
function fill(id,data){
var h=””;
for(var i=0;i
new Chart(document.getElementById(‘edvC5′),{
type:’bar’,data:{labels:vL,datasets:[{data:vD,backgroundColor:vC,borderRadius:3}]},
options:{indexAxis:’y’,responsive:true,maintainAspectRatio:false,
plugins:{legend:{display:false},tooltip:{callbacks:{label:function(c){return c.raw+’ %’}}}},
scales:{x:{grid:{color:grid},ticks:{color:txt,font:{size:10},callback:function(v){return v+’ %’}}},
y:{grid:{display:false},ticks:{color:txt,font:{size:11}}}}}
});
})();
Travelsoft Strengthens Its Position as Orchestra Acquires Afidium

The group announced, on July 30, 2026, the acquisition of Afidium by Orchestra, its French subsidiary specialized in the distribution and booking of travel. An operation that aims in particular to strengthen the complementarities between the solutions of the two companies.
Founded in 2005 by David Faveur and Patrick Rajaud, Afidium is a French company specialized in software for tourism professionals.
Its solutions cover several steps of the value chain, including tools for optimizing air fares, quality control of PNRs, quotation management and booking services across multiple sources.
The company also offers solutions dedicated to operations research, customer communication, management of air inventories as well as the booking of flights, accommodations and other services.
Des expertises complémentaires
The integration should enable the two companies to accelerate the development of their products and broaden the features offered to their clients. Orchestra’s customers will notably gain access to additional tools dedicated to air optimization and process automation.
For Afidium’s clients, they should benefit from increased development capacity as well as integration within a larger technological ecosystem.
“Afidium is a natural fit for Orchestra and Travelsoft. This combination will accelerate innovation and offer solutions spanning a broader scope to our clients“, said Christian Sabbagh, founder and CEO of Travelsoft.
Une continuité assurée pour Afidium
Afidium’s teams will also remain engaged with their current clients, while being able to rely on the resources of Orchestra and Travelsoft. “Joining Travelsoft allows us to develop our products at a larger scale, while maintaining the quality, expertise and responsiveness that our clients expect“, stated Afidium’s two co-founders.
The two companies now plan to progressively develop synergies between their products and to implement joint roadmaps for innovation. Travelsoft says it intends to prioritize developments likely to bring tangible benefits to tourism professionals.
Published by Amelia Brille TourMaG.com Editor View all articles by Amelia Brille
EDV Barometer: Orchestra – Reservations Fall 18% in May as Summer Slowdown Widens
French Vacation Observatory — June 2026
The Travel Agencies of France — Orchestra / Travelsoft
June 2026
The summer of 2026 looks set to be challenging for travel distributors. The latest edition of the French Travel Companies Observatory (EdV) and Orchestra confirms a clear slowdown in bookings. May departures still temper the overall drop.
Regarding departures through the end of May, the number of files is down 1.7% compared with the same period in 2025, while the business volume falls by 1.3%. The average basket edges up slightly by 0.4% to reach €1,555. It is worth noting that a significant portion of May travel had already been booked before the worsening situation in the Middle East.
France itself even records a 6.4% increase in business volume, while the medium-haul segment remains broadly stable. By contrast, the long-haul sector remains under pressure, with the number of files down 11.5% and turnover down by nearly 10%.
Destinations in the United States (-34.3%), Mexico (-22.7%), and Cape Verde (-12.6%) are among the hardest hit. Conversely, Albania (+342.6%), the Dominican Republic (+14%), and Croatia (+12.6%) continue to grow.
Summary:
– Bookings plunge in May
– An ever more retreating summer
Observatory — June 2026
Departures in May 2026
Market activity shows a slight dip: files down 2%, business volume down 1%, and the average basket nearly steady at €1,555. It should be noted that a significant share of May departures had already been booked prior to the deterioration in the Middle East situation.
Key indicators for departures through the end of May:
– Business volume: -1.3%
– Number of files: -1.7%
– Average basket: +0.4% (€1,555)
Geographic zones — departures May 2026 vs 2025
Top 20 destinations — departures May (number of dossiers vs 2025)
Note: A geographic breakdown and the list of top destinations are shown to illustrate regional and market concentration, with France and major outbound corridors highlighted.
Section 2 — May 2026 Reservations
Reservations in May 2026 show a sharp retreat: business volume down 21%, number of files down 18%, and the average basket down 4% to €1,632. The average lead time also contracts to 63 days, down 4 days versus 2025, signaling that bookings are being made increasingly closer to departure amid geopolitical uncertainties.
Key indicators for reservations in May 2026:
– Business volume: -21.3%
– Number of files: -17.9%
– Average basket: -4.3% (€1,632)
Lead time to departure: 63 days (-4 days vs 2025)
Geographic zones — reservations May 2026 vs 2025
Top 20 destinations — reservations May (number of dossiers vs 2025)
Geographic patterns and popular destinations for May reservations are presented, illustrating shifts in demand by region and corridor.
Section 3 — Summer Holidays 2026
Summer 2026 (July–August) reservations are down by 10.5% compared with 2025, both in terms of dossiers and business volume. The average basket remains stable at €2,710. All zones show declines, with long-haul the most affected, posting a 20% drop in dossiers.
Key indicators for Summer 2026:
– Business volume: -10.5%
– Number of dossiers: -10.5%
– Average basket: +0.0% (€2,710)
Geographic zones — reservations summer 2026 vs 2025
Typologies of travelers — Summer 2026
A snapshot of traveler types for the summer shows the following profiles:
– Solos: 3.1% of dossiers; -15.7% in dossiers; €1,700 on average
– Duos: 34.3% of dossiers; -11.8% in dossiers; €2,302 on average
– Families: 48.0% of dossiers; -10.1% in dossiers; €2,753 on average
– Groups: 14.5% of dossiers; -7.6% in dossiers; €3,748 on average
Categories of stays — Summer 2026
The distribution of stays by category for the summer shows:
– Packages: -9.8%; Basket up 1.2% to €2,772
– Accommodations: -11.8%; Basket up 0.1% to €1,141
– Circuits: -15.9%; Basket down 3.9% to €5,823
Top 10 destination cities — Summer 2026
Top 10 destination cities for the summer of 2026 are presented, illustrating the geographic spread of demand across leading urban and resort destinations.
Footer
Source: Observatoire des Vacances des Français — The Travel Companies of France (Les Entreprises du Voyage) · Orchestra / Travelsoft — June 2026
Data drawn from travel agencies using the Orchestra platform (20+ brands, minimum of 2 years).
