
By the end of July, departures showed a 5.6% drop in the number of files compared with July 2025. Sales volume fell by 4.5%, while the average basket rose by 1.2%, to €2,098. However, the increase in the basket is not sufficient to offset the contraction in volumes.
France sees its sales volume fall by 4%, with the number of bookings down by 7%. The 4% increase in the average booking value helps to limit the impact. The short- to medium-haul segment displays better resilience, with a sales volume down by only 1.9% and the number of bookings down by 2.7%.
Long-haul, however, remains the market’s main fragility point. The number of bookings drops by 18.5% and the sales volume by 17.6%, despite a slight uptick in the average spend.
The Top 20 destinations illustrate this polarization. France remains at the top despite a 7.2% decrease, while Spain edges up by 4.1%. Morocco (+6.4%), Albania (+288.2%), Japan (+28.3%), and Norway (+15.8%) are among the main growth destinations.
Conversely, several markets post steep declines: Turkey (-35.3%), the United States (-39.1%), Egypt (-22.5%), Portugal (-20.8%), and Tanzania (-23.9%).
A slowdown compared to July 2025: business volume -4.5%, bookings -5.6%, with the average spend up slightly (+1.2%) at €2,098. The rise in spend does not compensate for the drop in volumes; the market is clearly slowing down in demand.
Medium-haul
Long-haul
Reservations stabilize: turnover is almost flat (-0.3%), bookings down (-3.7%), while the average spend increases (+3.5% to €1,909). The market remains more supported by value than by volumes.
Medium-haul
Long-haul
As August 2026 departures approach: reservations remain lower than 2025 — turnover down 7.5%, bookings down 9.1% — despite a rise in the average spend (+1.7% to €2,289). Long-haul remains the most fragile segment (-18% in bookings).
Medium-haul
Long-haul
Departures & reservations July: 01/07 – 28/07/2026 · August: reservations 01/01 – 28/07/2026, departures 01/08 – 31/08/2026.
Data drawn from travel agencies using the Orchestra platform (20+ brands, minimum 2 years).
EDV Barometer: Orchestra Reservations Rebound in August, but Summer 2026 Remains Lagging
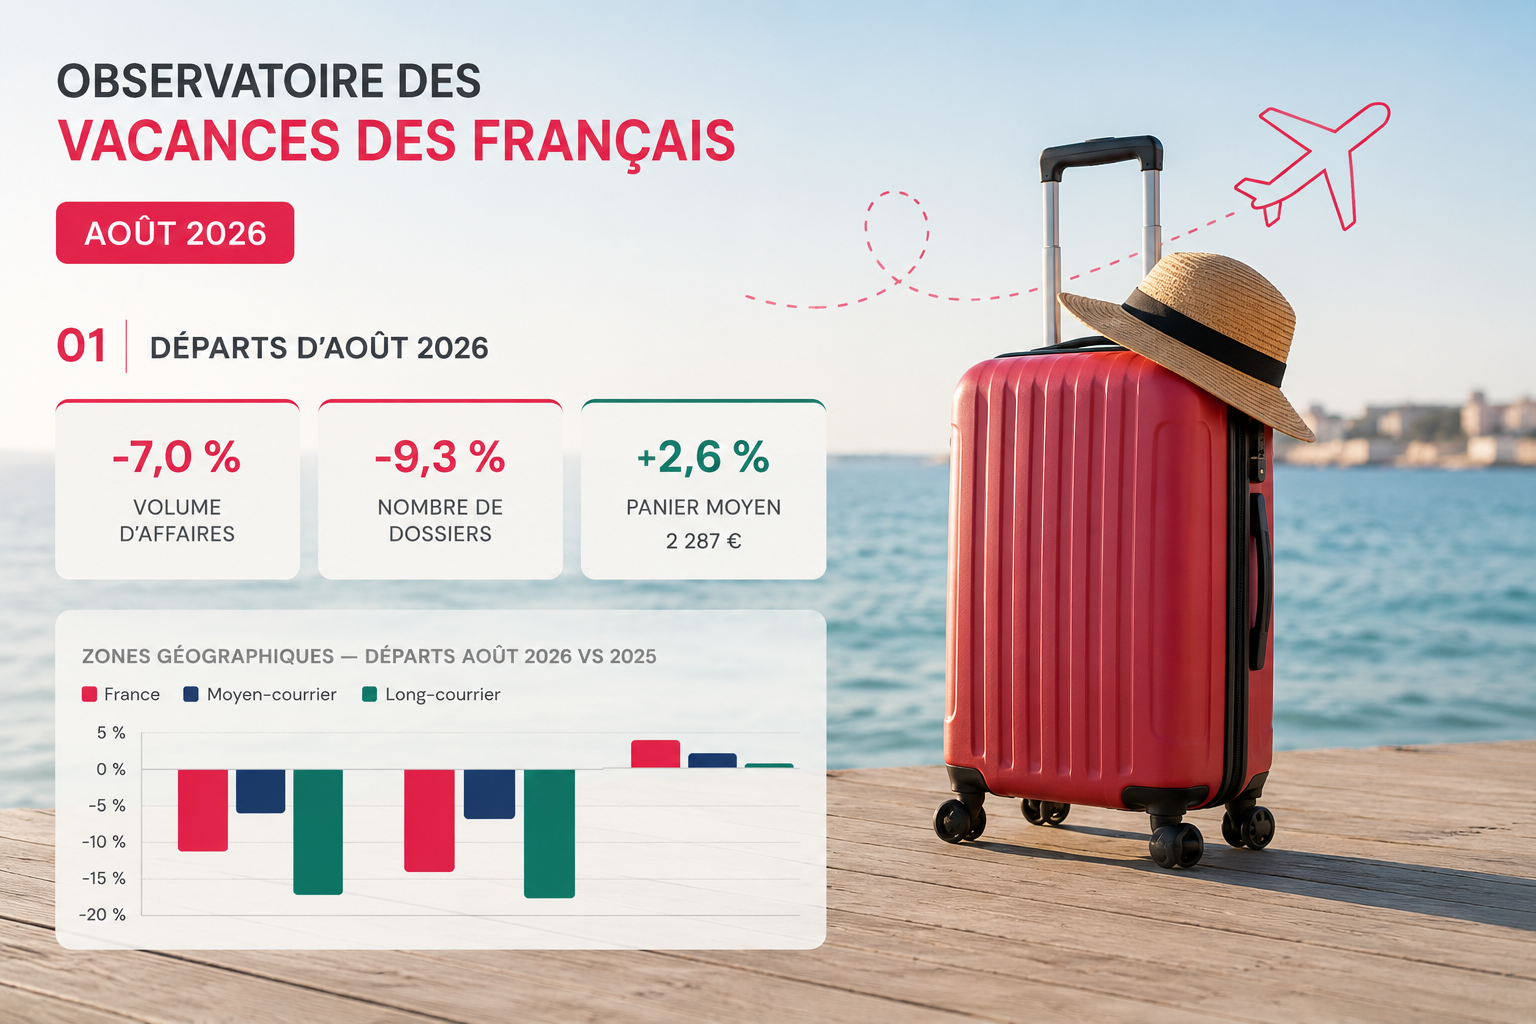
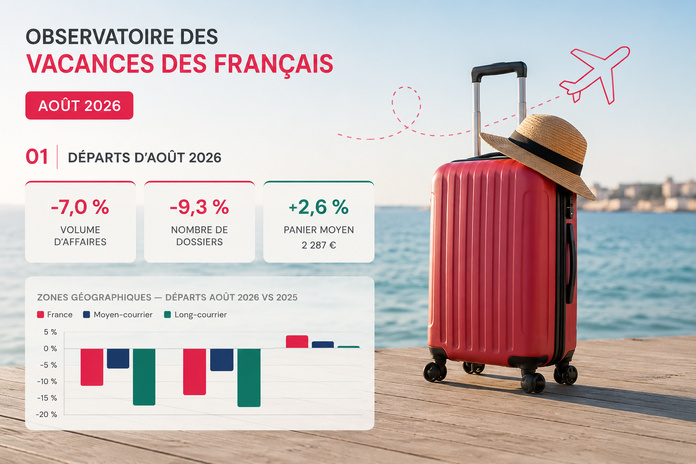
According to the new Observatory of French Holidays EDV-Orchestra, departures recorded from August 1 to 26 show a 9.3% drop in the number of bookings and a 7% decline in business volume compared with August 2025. The rise in the average basket, from 2.6% to €2,287, only softens the decline.
However, the data reveal a positive signal: bookings made in August are rising again.
In August 2026, the number of bookings grows by 2.9% year on year while the business volume leaps by 7.6%. The average basket reaches €1,697, up 4.6%.
The average booking lead time indeed stands at 55 days, i.e., two days longer than in 2025. More importantly, the share of bookings made less than 30 days before departure drops to 46.2%, compared with 49.7% a year earlier. Conversely, bookings made more than 90 days in advance rise slightly, to 18.9% versus 18% in 2025.
The recovery in sales thus does not signal a mass shift to last-minute bookings, but rather a slight reintroduction of forward planning in booking behaviors, explains the barometer.
The infographic: numbers at a glance
Confirmed slowdown compared to August 2025: business volume -7.0%, bookings -9.3%, average basket up (+2.6%) to €2,287. The rise in the basket does not offset the decline in volumes; the summer season remains downward oriented. Long-haul remains the most affected segment (-16.1% in bookings).
Medium-haul
Long-haul
Recovery in the trend after several months of decline: the business volume returns to positive (+7.6%), supported by a rise in bookings (+2.9%) and in the average basket (+4.6% to €1,697). The average booking lead time is 55 days, two days longer than in 2025.
Medium-haul
Long-haul
To date, reservations for September 2026 departures remain below 2025: business volume -5.4%, bookings -5.8%, average basket almost stable (+0.4% at €1,959). Long-haul concentrates the sharpest decline (-16.6% in bookings).
Medium-haul
Long-haul
Departures & reservations August: 01/08 – 26/08/2026 · September: reservations 01/01 – 26/08/2026, departures 01/09 – 30/09/2026.
Data from travel agencies using the Orchestra platform (20+ brands, at least 2 years).
‘;
}
function fill(id,data){
var h=””;
for(var i=0;i
new Chart(document.getElementById(‘edvC5′),{
type:’bar’,data:{labels:vL,datasets:[{data:vD,backgroundColor:vC,borderRadius:3}]},
options:{indexAxis:’y’,responsive:true,maintainAspectRatio:false,
plugins:{legend:{display:false},tooltip:{callbacks:{label:function(c){return c.raw+’ %’}}}},
scales:{x:{grid:{color:grid},ticks:{color:txt,font:{size:10},callback:function(v){return v+’ %’}}},
y:{grid:{display:false},ticks:{color:txt,font:{size:11}}}}}
});
})();
Flight Deals Barometer: Maghreb Leads Summer Flight Searches

By contrast, overseas destinations continue to be affected by airfares. Saint-Denis de La Réunion falls by 55%, while Pointe-à-Pitre (-67%) and Fort-de-France (-22%) also register steep declines.
“Mid-summer data confirm the Maghreb’s leadership and the rebound of certain European and African routes,” notes Caroline Gachet, Marketing & E-commerce Director at Bourse des Vols.
Du côté de l’Europe et du long-courrier, Porto records a 78% rise and reaches the 6th place. The strongest upsurge, however, goes to Abidjan, up 250%, which climbs to 7th. Bangkok, third in the ranking, drops by 34%. Mauritius completes the Top 10 with a 17% increase.
From provincial airports, searches also confirm the appeal for the Maghreb and Africa, notably Marrakech up in Lyon (+60%), Tunis in Nice (+91%), and Oran in Toulouse (+78%). Porto also shows strong progress, notably from Bordeaux (+204%), Toulouse (+179%) and Lyon (+128%). In Marseille, searches to Annaba (Algeria) jump 291%, while Miami grows by 470%.
The Indian Ocean and Asia Make a Strong Showing for All Saints’ Day
Saint-Denis remains first, ahead of Algiers, while Marrakech climbs two places to take 3rd place. Mauritius achieves one of the sharpest gains, leaping four places to reach 4th position.
The momentum is even more striking for Antananarivo, which vaults 22 places to reach 7th, and Nosy Be, which adds four places. In Asia, Bangkok stays in the Top 5 despite slipping one place, while Tokyo advances 19 ranks to enter 9th.
“For All Saints’ Day, there is a clear tilt toward the Indian Ocean and a strong comeback for Asia,” highlights Caroline Gachet.
The Caribbean remains present but in a scattered pattern: Pointe-à-Pitre loses three places and ends up 6th, while Fort-de-France gains one place and closes the Top 10.
TOP 10 from France
TOP 10 from Paris and 7 provincial airports
TOP 10 All Saints’ Day Holidays
✈ TOP 10 DESTINATIONS
From France in search volume – July-August 2026
✈ TOP DESTINATIONS
‘;
}
if (v === 0) {
return ‘
‘;
}
if (v ▼‘ + fmt(Math.abs(v)) + ‘ %
‘;
}
return ‘
‘;
}
var tabsEl = document.getElementById(“tmTabs”);
var rowsEl = document.getElementById(“tmRows”);
var subEl = document.getElementById(“tmSubtitle”);
function render(idx) {
var ville = VILLES[idx];
var html = “”;
for (var i = 0; i ‘
+ ‘
+ ‘
‘
+ ‘
‘
+ ‘
‘
+ varCell(r.v)
+ ‘
‘;
}
rowsEl.innerHTML = html;
subEl.innerHTML = ‘In volume of searches · starting from
‘ + ville.label + ‘
· July-August 2026′;
var btns = tabsEl.getElementsByTagName(“button”);
for (var b = 0; b
EDV-Orchestra Barometer: Bookings Rise in June, but Summer Remains Below 2025 Levels

While SETO announced on Thursday July 2 a deficit of 85,000 customers for the summer, the latest Orchestra figures – which, recall, only account for reservations made through this channel (custom trips, stays booked directly on TOs’ B2B, or the dynamic package created by agencies are notably excluded) – also show that, by the end of July, reservations for departures in July-August 2026 were lower than those of the previous year.
The number of files continues to fall by 8.2%, with a business volume down 7.9%. However, the trend is gradually improving: the lag was still about 10% a month earlier.
The medium-haul segment once again demonstrates the strongest resilience (-5.7% in dossiers), while long-haul continues to suffer (-19.2%). Travelers continue to favor nearby destinations, to the detriment of longer journeys.
Among the most dynamic destinations for the summer are Albania (+255%), Montenegro (+21%), Canada (+12%), Norway (+7%), Morocco (+4.5%), and the Dominican Republic (+2.3%). Spain manages to hold (+0.2%), while France, Greece, Egypt, Turkey or the United States remain down.
Summary:
June departures still lag behind
June reservations rebound
A marked retreat compared with June 2025: business volume -4.9%, dossiers -5.5%, with the average basket rising slightly (+0.7%) to €1,567. These results confirm a cautious entry into the summer period.
Medium-haul
Long-haul
Net improvement in bookings: business volume turns positive again (+2.3%) after a -21% in May, driven by an average basket up (+3.9% to €1,868) which compensates for the slight drop in dossiers (-1.6%). The average lead time stands at 60 days (-1 day vs 2025).
Medium-haul
Long-haul
Summer July-August 2026: reservations still behind (volume -7.9%, dossiers -8.2%), but the decline is narrowing compared with late May. The average basket is almost stable at €2,490 (+0.3%). Long-haul remains the most affected (-19% in dossiers).
Medium-haul
Long-haul
Data drawn from travel agencies using the Orchestra platform (20+ brands, at least 2 years).
‘;
}
function fill(id,data){
var h=””;
for(var i=0;i
new Chart(document.getElementById(‘edvC5′),{
type:’bar’,data:{labels:vL,datasets:[{data:vD,backgroundColor:vC,borderRadius:3}]},
options:{indexAxis:’y’,responsive:true,maintainAspectRatio:false,
plugins:{legend:{display:false},tooltip:{callbacks:{label:function(c){return c.raw+’ %’}}}},
scales:{x:{grid:{color:grid},ticks:{color:txt,font:{size:10},callback:function(v){return v+’ %’}}},
y:{grid:{display:false},ticks:{color:txt,font:{size:11}}}}}
});
})();
Creation of the First Barometer for Independent Tourism Professionals

That of Entreprises du Voyage, based on Orchestra data, omits sales of tailor-made trips made with inbound operators or built by stacking services.
These gaps are gradually being filled, for example thanks to data provided by Civitatis.
To reflect the industry more accurately, Travel Force, in partnership with IFTM, launches the first Barometer of tourism independents.
“Independents are everywhere in tourism, but nowhere in the figures.
We talk about them, we work with them, but no one had ever really listened to them on a national scale. This barometer finally gives them a statistical presence and the more responses there are, the more their voice will be heard“, announces Olivier Charmes, president of the consulting and operational reinforcement agency.
Barometer of tourism independents: questionnaire open until end of July
It consists of several questions and takes between five and six minutes. It aims to establish an unprecedented snapshot of the market for tourism independents in 2025, based on practices, revenues and existing models, and then to reveal the real on-the-ground issues.
To participate in the barometer, click here.
Independent tourism professionals can respond until July 31, 2026, for an activity analysis covering January 1 to December 31, 2025.
After that, the responses will be analyzed and anonymized. No ranking will be established, but an overview of these players will be drawn.
The consolidated results of the study will be available at the IFTM trade show, during a conference on September 17 at 2:30 PM, in room Agora.
“The overarching theme of this edition of IFTM is to reveal the value created by travel, and independents contribute a crucial, often invisible, portion of that value in daily life. Welcoming the presentation of this first barometer was an obvious step: it provides the entire industry with data that were missing to understand these professionals and to work with them,” Marie Allantaz, editorial director and strategic management at IFTM.
Among independents, we find consultants, travel planners, trainers, content creators, guides, business introducers, journalists, outsourced salespeople, industry experts…
EDV Barometer: Orchestra – Reservations Fall 18% in May as Summer Slowdown Widens
French Vacation Observatory — June 2026
The Travel Agencies of France — Orchestra / Travelsoft
June 2026
The summer of 2026 looks set to be challenging for travel distributors. The latest edition of the French Travel Companies Observatory (EdV) and Orchestra confirms a clear slowdown in bookings. May departures still temper the overall drop.
Regarding departures through the end of May, the number of files is down 1.7% compared with the same period in 2025, while the business volume falls by 1.3%. The average basket edges up slightly by 0.4% to reach €1,555. It is worth noting that a significant portion of May travel had already been booked before the worsening situation in the Middle East.
France itself even records a 6.4% increase in business volume, while the medium-haul segment remains broadly stable. By contrast, the long-haul sector remains under pressure, with the number of files down 11.5% and turnover down by nearly 10%.
Destinations in the United States (-34.3%), Mexico (-22.7%), and Cape Verde (-12.6%) are among the hardest hit. Conversely, Albania (+342.6%), the Dominican Republic (+14%), and Croatia (+12.6%) continue to grow.
Summary:
– Bookings plunge in May
– An ever more retreating summer
Observatory — June 2026
Departures in May 2026
Market activity shows a slight dip: files down 2%, business volume down 1%, and the average basket nearly steady at €1,555. It should be noted that a significant share of May departures had already been booked prior to the deterioration in the Middle East situation.
Key indicators for departures through the end of May:
– Business volume: -1.3%
– Number of files: -1.7%
– Average basket: +0.4% (€1,555)
Geographic zones — departures May 2026 vs 2025
Top 20 destinations — departures May (number of dossiers vs 2025)
Note: A geographic breakdown and the list of top destinations are shown to illustrate regional and market concentration, with France and major outbound corridors highlighted.
Section 2 — May 2026 Reservations
Reservations in May 2026 show a sharp retreat: business volume down 21%, number of files down 18%, and the average basket down 4% to €1,632. The average lead time also contracts to 63 days, down 4 days versus 2025, signaling that bookings are being made increasingly closer to departure amid geopolitical uncertainties.
Key indicators for reservations in May 2026:
– Business volume: -21.3%
– Number of files: -17.9%
– Average basket: -4.3% (€1,632)
Lead time to departure: 63 days (-4 days vs 2025)
Geographic zones — reservations May 2026 vs 2025
Top 20 destinations — reservations May (number of dossiers vs 2025)
Geographic patterns and popular destinations for May reservations are presented, illustrating shifts in demand by region and corridor.
Section 3 — Summer Holidays 2026
Summer 2026 (July–August) reservations are down by 10.5% compared with 2025, both in terms of dossiers and business volume. The average basket remains stable at €2,710. All zones show declines, with long-haul the most affected, posting a 20% drop in dossiers.
Key indicators for Summer 2026:
– Business volume: -10.5%
– Number of dossiers: -10.5%
– Average basket: +0.0% (€2,710)
Geographic zones — reservations summer 2026 vs 2025
Typologies of travelers — Summer 2026
A snapshot of traveler types for the summer shows the following profiles:
– Solos: 3.1% of dossiers; -15.7% in dossiers; €1,700 on average
– Duos: 34.3% of dossiers; -11.8% in dossiers; €2,302 on average
– Families: 48.0% of dossiers; -10.1% in dossiers; €2,753 on average
– Groups: 14.5% of dossiers; -7.6% in dossiers; €3,748 on average
Categories of stays — Summer 2026
The distribution of stays by category for the summer shows:
– Packages: -9.8%; Basket up 1.2% to €2,772
– Accommodations: -11.8%; Basket up 0.1% to €1,141
– Circuits: -15.9%; Basket down 3.9% to €5,823
Top 10 destination cities — Summer 2026
Top 10 destination cities for the summer of 2026 are presented, illustrating the geographic spread of demand across leading urban and resort destinations.
Footer
Source: Observatoire des Vacances des Français — The Travel Companies of France (Les Entreprises du Voyage) · Orchestra / Travelsoft — June 2026
Data drawn from travel agencies using the Orchestra platform (20+ brands, minimum of 2 years).
Paris Tourism Barometer: April 2026 Stable Despite Air Travel Dip

The period was notably boosted by the Paris Marathon, the Francophone Diabetes Society Congress, and the Easter long weekend.
Hotel RevPAR, however, advanced compared with 2025 thanks to a slight increase in the average price, even as the occupancy rate fell by 0.3 percentage point.
Air arrivals nonetheless recorded a 2.3% decline for the month of April versus 2025. The business segment rose slightly (+2.7%), while the group travel clientèle dropped by 17.4%.
What about spring?
This trend is also reflected in hotel performances, with a 3.3% decrease in occupancy on the May 1st weekend, versus a 2.6% increase on the May 8 weekend.
Early estimates for the month of June point to a 10.9% decline in air bookings and a predicted 4.3% drop in hotel occupancy.
Several events are expected to support summer activity, notably The Weeknd concerts at the Stade de France in July, Bad Bunny performances at Paris La Défense Arena, and several international congresses held at Paris Expo Porte de Versailles and the Palais des Congrès.
The 2026 European Swimming Championships, staged between Paris and Saint-Denis from July 31 to August 16, should also help bolster tourist attendance during the summer.
