Rising Kerosene Prices: Could They Trigger a Domino Effect?


Depositphotos.com Auteur msavoia

CroisiEurope


When will the emotional rollercoaster stop?

After the bright prospects at the start of the year, disaster struck! The American and Israeli strikes on Iran on February 28 last put a halt to activity. A very sluggish spring followed, marked by fears of a kerosene shortage, compounded by a stagnant travel market hampered by the geopolitical backdrop and fare prices that keep climbing…

The professionals soldier on against the odds and muddle through the summer, with a season marked by last-minute sales. Then activity brightened again in August and early September.

A breath of fresh air. We want to believe. It will restart, despite a recovery that feels fragile, the professionals want to believe and move forward. This was at least the predominant sentiment at IFTM. The aisles were busy, the momentum seemed positive once more.

Alas, behind the smiles, other concerns emerged, including the surge in kerosene prices that raises fears of difficult days for the airlines.


Fuel could account for between 40 and 45% of operating costs for these carriers, versus 25% last year. That could jeopardize the business models of carriers, especially the low-cost ones.

If some airlines have fuel hedges, there will still be far from fifty solutions to cope with the rise if one excludes the slashbacks in flight schedules, cancellations, or further price increases.

Volotea illustrates the situation well. The Spanish low-cost carrier trimmed its winter program, announcing numerous route suspensions. But as one train can hide another, it is the tour operators and agencies, but also the customers who pay the price.

Re-protection, searching for a Plan B: travel operators know how to do it. But at what cost? Mobilizing teams, advancing incidental costs, taking charge, even though the plane ticket has been paid long ago… As Patrice Caradec said in our pages: “I am worried about Volotea, but I am also worried about air transport.” That is why the industry is condemned to pilotage by sight.

Which company to book, which routes will be adjusted? Are there risks of bankruptcy? Whatever happens, we know that operators will have to foot the bill…


That is troubling, especially since professionals had bet on the rise of low cost carriers to push dynamic packaging and other “flex” offers.

In the face of this business model under severe strain, one wonders whether the good old charters should make a comeback… A broad debate that we won’t open here!

And then there is the question of prices. If airlines pass part of the fuel increase onto ticket prices, it creates a domino effect, with the entire chain at risk of paying the price.

Indeed, purchasing power remains a central concern, and the last-minute sales seen this summer testify to it: people compare, wait, monitor prices… and book at the last moment.

With an average diesel price at the pump of €2.23 per liter in Europe (a record!), and petrol following the same curve, we can easily understand that going on vacation may not be the main concern of our dear fellow citizens.

Not to mention that this is not the only expense category that is rising… When the barrel climbs, everything climbs!

Vigilance remains essential. After the greetings in the aisles at IFTM, returning to the office feels somewhat dull knowing that other issues loom, with the 2027 Finance Bill and the presidential elections… Not to mention potential strikes and more structural transformations: the sector’s attractiveness or even artificial intelligence.

Come on, let’s keep our spirits up!
Fuel Prices: Airlines Face the Moment of Truth [ABO]


Le carburant provoque rarement, à lui seul, la faillite d’une compagnie. Il agit plutôt comme un révélateur et parfois comme le détonateur final - Depositphotos.com, svedoliver

CroisiEurope


In my column published on April 22, “Aviation in the Face of the Great Slowdown,” I was already analyzing the surge in jet fuel following the outbreak, on February 28, 2026, of the conflict in Iran.

This shock now imposes concrete decisions: which routes to keep, at what price, and with which aircraft?

For an industry whose margins remain structurally thin, a sustained rise in fuel can quickly undermine the profitability of a single route, then the network, and in the most fragile cases, even threaten the survival of a company.


An Immediate Shock to Margins That Are Razor-Thin

Fuel, alongside staff, constitutes one of the main expenditure items for an airline.
Its weight varies with the fleet, the business model, and the price of fuel.

But with margins often limited to just a few euros per passenger, a sustained rise can quickly erase the anticipated profit.

Filling the aircraft is no longer enough. A route with a load factor of 95% can easily lose money if it mainly carries passengers who bought low-cost tickets.


Fuel Hedging Only Delays the Hit

Fuel hedges temporarily shield margins. They allow certain carriers to keep their fares while competing players already bear the higher costs.

But they do not eliminate either the risk on uncovered volumes or the risk of renewing contracts at higher prices.

The dollar adds a currency risk: a company whose revenues are collected in a weaker currency can simultaneously face the rise of jet fuel and that of its invoicing currency.

Ryanair illustrates the advantage, but also the limits, of this protection. For its fiscal year from April 2026 to March 2027, the group hedged 80% of its jet fuel needs at around $67 per barrel. In the first quarter, the 20% uncovered cost nearly $150 per barrel, more than double year over year, while the average fare fell by 6%. Despite hedging, the fuel bill rose by 16% and net income fell by 34%.

Qatar Airways illustrates another trade-off. Its chief executive, Hamad Al-Khater, calls the current crisis the most significant in the airline’s history. In an interview with Bloomberg TV reported on September 20, he mentions jet fuel around $182 per barrel, about 90% above its level at the end of February 2026. Qatar is not yet passing this extra cost directly to passengers: it is prioritizing the most profitable routes and temporarily suspending less performing services.

Fuel no longer weighs solely on margins; it also shapes capacity and the network.


Medium-Haul: Reducing Without Undermining the Network

On the medium-haul, airlines have a degree of flexibility. They can cut a frequency, suspend a route during the winter, close a base, or redeploy an aircraft to a more profitable destination.

The first casualties will be the marginal routes: those kept to fill a slot, defend a market position, or deter a competitor from entering, but whose profitability remains insufficient.

Moving from three daily flights to two more-filled rotations reduces overall consumption. But this saving can make the offering less attractive to business travelers and reduce the chances for connections.

The major low-cost carriers, with their low unit costs and their ability to redeploy aircraft, can profit from the withdrawal of weaker players.

Traditional carriers have other advantages: premium customers, cargo and connections. Yet their cost structure and the interdependence of routes complicate capacity reductions.


Will We Need to “Break Up the Schedules”?

During the IFTM 2026 trade show, last week, one of France’s leading aviation experts told me: “To get out of this, we’ll have to break up the schedules.” It may no longer be enough to simply suspend a few underperforming routes.

For the most exposed airlines, it will be necessary to reconsider the very architecture of their network, abandon certain historic positions, and concentrate resources on the routes that can preserve cash flow.

The task is particularly difficult. Routes do not operate independently. Some feed a hub or enable a profitable long-haul connection.

Removing a seemingly loss-making service can therefore weaken other routes that seemed profitable. Modifying a program already marketed also incurs costs: rerouting passengers, refunding tickets, reorganizing crews, losing connections, and tarnishing the airline’s image.


Who Will Trim Capacity First?

A reduction in capacity can improve load factors and support fares. But no airline necessarily wants to be the first to act.

Each may hope that a competitor will drop frequencies or abandon a route before them. They could then maintain their offering, win back some passengers, and benefit from price increases triggered by capacity reductions.

We are witnessing a form of poker game. The carrier that cuts its schedule first risks giving up slots and market share. Those that wait too long may continue to operate flights that drain their cash flow.

Capacity discipline is gaining ground: Lufthansa has already announced short-haul reductions, while Air France-KLM is curbing growth and redeploying aircraft toward the most promising markets. Reducing a network can be decided quickly. Rebuilding it may take years.


The Passenger Will Ultimately Pay

The rise in fuel costs will not be immediately passed on to tickets.

On a highly competitive route, an airline cannot raise fares alone without losing customers. It will probably start by reducing promotions, limiting the cheapest fare classes, and increasing ancillary revenues: baggage, seats, priority boarding, or onboard services.

The reduction in capacity can also help sustain prices: when a service disappears or a competitor pulls out, seats become scarcer. The passenger may then face higher-priced tickets, less choice, and less convenient schedules.


Can Fuel Trigger Bankruptcies?

Fuel rarely causes the bankruptcy of an airline on its own. It acts more as a revealer and sometimes as the final detonator.

The most threatened carriers will be those with insufficient cash reserves, high indebtedness, expensive aircraft leases, an aging fleet, weak fuel hedging, and unprofitable routes.

Independent carriers without a major shareholder, some regional operators, and long-haul models that rely primarily on very low fares appear particularly vulnerable.

Therefore, the first airline to fail will not necessarily be the one that consumes the most fuel, but the one with the least time to react and not enough money to hold on.


The Hour of Decisions

In the short term, airlines must protect their cash, adjust their fares to demand, and shrink capacity that no longer covers costs.

In the medium term, they must continue to refresh fleets and develop partnerships, despite financing and delivery constraints.

The question is no longer whether airlines will raise prices or cut programs. They will probably do both.

The remaining question is who will be willing to move first and who can afford to wait. In air transport, bankruptcies are rarely caused by a single event. But for some carriers, the surge in jet fuel could well be the last drop in the tank.


Eric Didier - DR

A passionate entrepreneur and specialist in air transport, with more than three decades of experience, Eric Didier coordinated the launch of the Oneworld alliance before creating and developing Qatar Airways in France and on several European markets, where he held key leadership positions, ensuring the growth and success of the airline.

An expert in team management and in commercial strategies, alliances and distribution, he has worked with several major airlines, contributing to their international expansion.

He now leads the consulting firm TED Advisory Services.

Business Travel in 2027: Market Growth Driven by Rising Prices


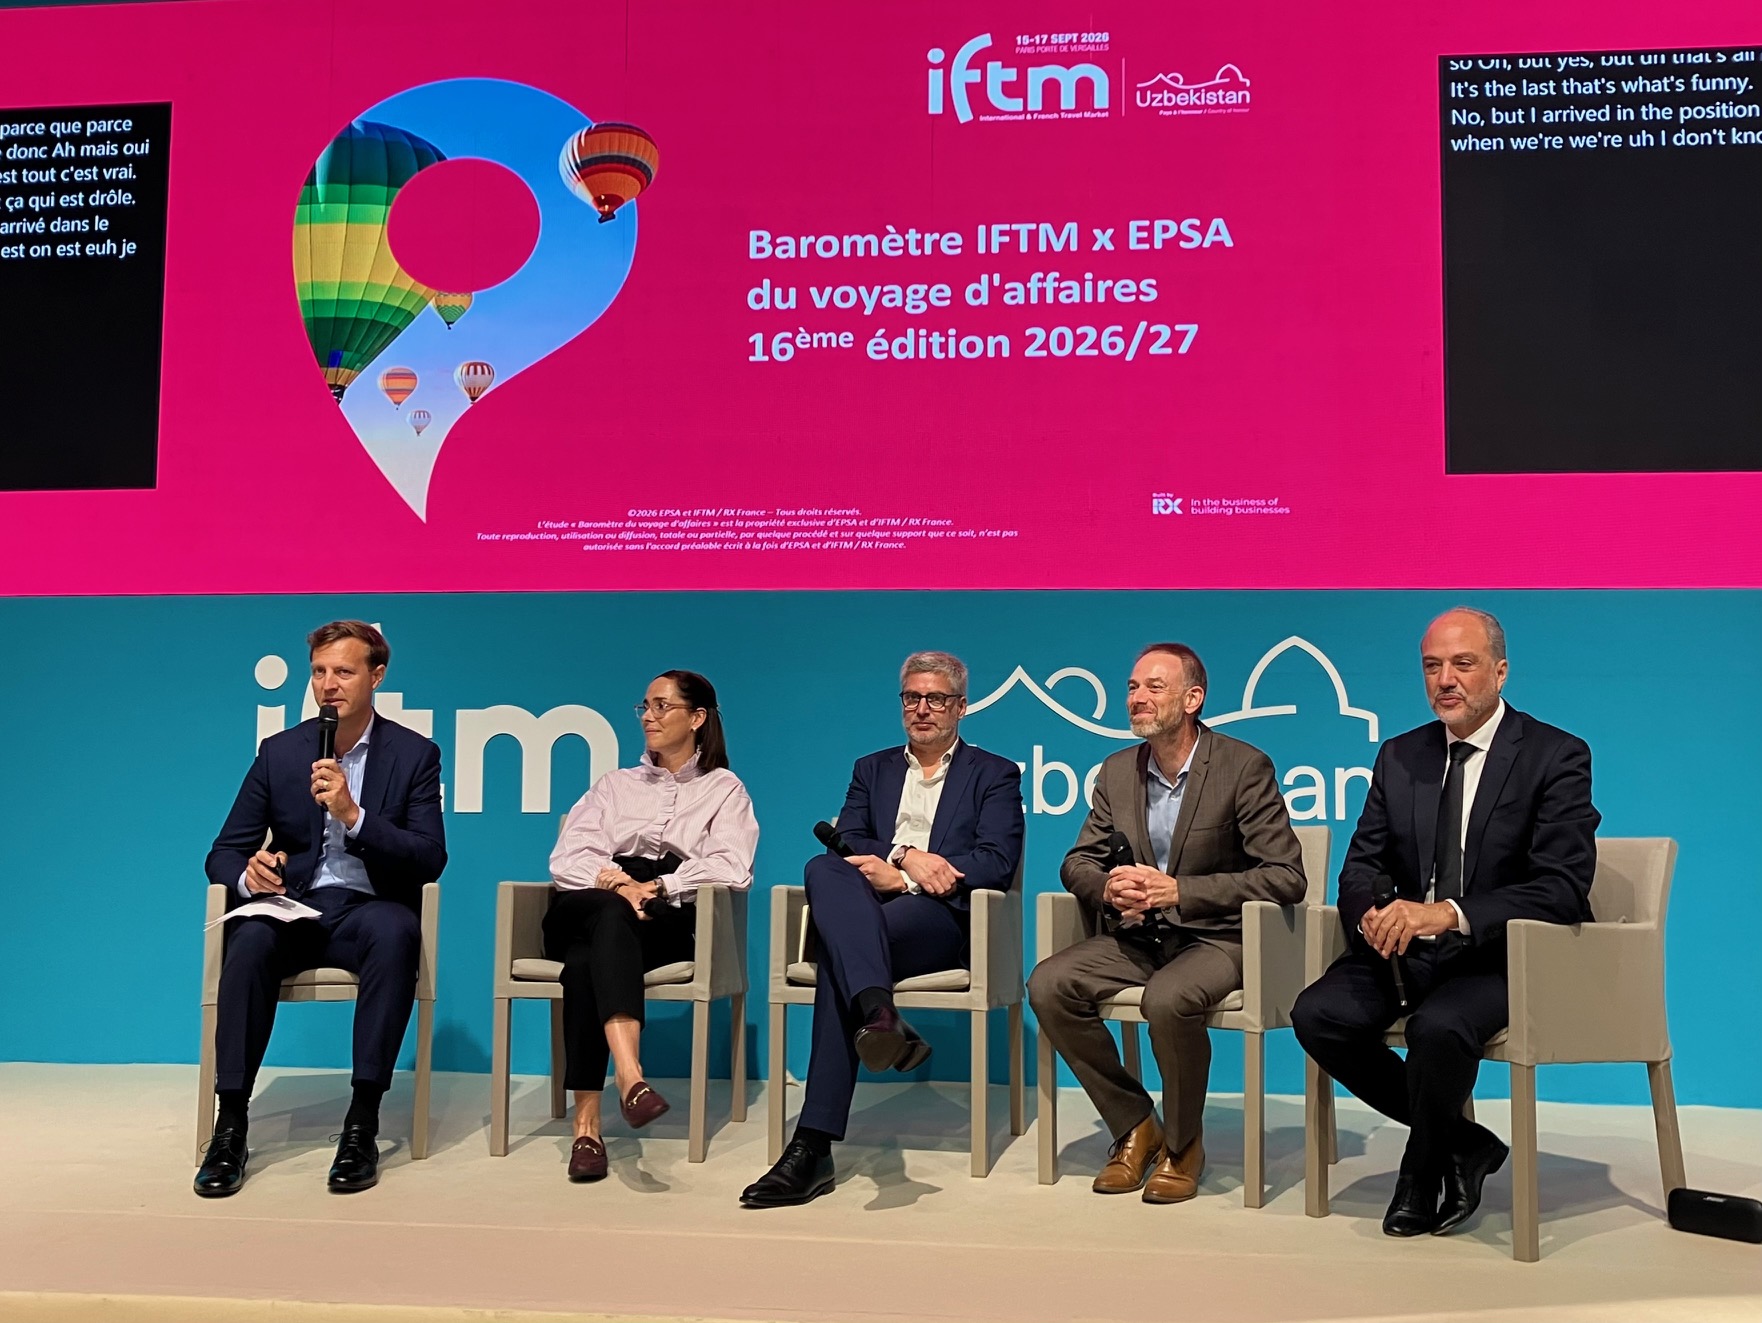
Le baromètre du voyage d'affaires, lors du salon IFTM. Photo: TB

CroisiEurope


Turned into a fixed appointment, the annual IFTM-EPSA barometer of business travel is eagerly awaited by travel agencies specializing in corporate travel and by companies.

In a context of geopolitical and economic tensions, the IFTM hall was well attended on September 16 for the presentation of the 2026/27 edition.

Forecasts are especially uncertain as the 2026 uncertainties are likely to spill over into 2027, with a little extra: presidential and perhaps legislative elections in France!

It is therefore with great caution that the travel-industry consulting firm EPSA unveiled its projections.

The year 2026 is expected to close with a French business travel market of €31.6 billion, up 2.3%. For 2027, EPSA forecasts €32.7 billion, up 3.5% compared with 2026.


Questioning Airfare Prices

This trend is nevertheless deceptive as the forecast for France’s GDP growth in 2026 was revised downward to 0.4% by the Banque de France, which hopes for a slight rebound in 2027, to 0.9%.

The growth of the business travel market should indeed be largely driven by inflation, while “demand is expected to show near-stability, at -0.2%. Since 2020, clients and suppliers have learned to cope with successive crises” comments EPSA.

The greatest uncertainty lies in air travel prices, as kerosene prices surge again and the airlines are buying their fuel stocks for next year.

EPSA estimates that air travel prices could jump by 3.7% to 4.4% globally in 2027, and between 4.2% and 4.5% on the domestic market alone, with a confidence index on this forecast of only 6/10 as uncertainties persist.


Fuel Costs Up 53%!

Already in the first half of 2026 versus 2025, long-haul prices surged by 4.8%, versus 1.9% for short/medium haul and 2.6% in France, driven by kerosene prices, of course (the fuel cost per flight hour for an Airbus A320neo rose by 53% in September compared with January 2026) but also by higher airport taxes.

There remains a strong international demand but “with purchasing behaviors changing for companies, through later bookings,” notes David Marey of Air France.

It is also worth noting the low penetration of NDC: “about one in three bookings in France for business travel is made this way at Air France, compared with 60% for leisure. The education work must continue,” adds him.

Also read : Business travel: how travel managers revise their criteria to control costs


The Transformation of Europe’s Skies Accelerates

In the end, total air traffic for the year 2026 is expected to reach 5.1 billion passengers worldwide. Even so, in France it slips slightly by 0.8% in the first half.

In this context, IATA expects a 50% drop in airline profits in 2026, with a continued consolidation of the global skies.

In Europe alone, the Lufthansa group will control 90% of Italian ITA Airways by early 2027.

The American investment fund Apollo acquired easyJet last August and the entry of Air France-KLM or Lufthansa into the capital of TAP Portugal, as part of the privatization of the latter, is set to be approved in the coming months.


Train: Competition Slow to Emerge

For rail, price growth in 2027 should be more modest, between 1.4% and 1.7% in France, and between 1.8% and 2.2% in Europe.

This is due to higher toll costs for using infrastructure and sustained demand growth, with a need for companies to decarbonize their business travels.

And yet the supply side is slow to respond: the opening to competition, which could influence prices, is slow to materialize. On the Paris–Lyon route, the arrival of Trenitalia has translated into a 20% increase in traffic over six years, with an average price drop of -10%.

And the new generation TGVs promised by SNCF for the Paris–Marseille route for the 2024 Olympics, with higher capacities, are still awaited. The operator now hopes for service before the end of the year.

Ten sets have been delivered so far (out of 115 ordered) but technical problems delay their commercial start.

In the west (Brittany, Bordeaux…), competition influence on prices will have to wait until at least 2028, with the first trains of the newly licensed Velvet company, which has ordered 12 sets.


Céline Dion Boosts Parisian Hotel Traffic


Amex GBT/CWT: The Merging Giants Shake Up the Field

Finally, in this still uncertain context, consolidation is also underway among TMCs to better control costs and provide comprehensive service to their clients.

The acquisition of Carlson Wagonlit Travel (CWT) by Amex GBT in 2025 gave birth to a new giant, whose business volume is expected to rise from €31 billion last year to €44 billion (including CWT integration) this year.

There is also the alliance between AMEX GBT and SAP Concur in 2025, with the launch of the offering Complete, a new co-developed solution based on artificial intelligence, which combines bookings, services, payments and expense management.

Far behind, the top 5 TMCs include BCD Travel (€21 billion), Navan (€7.8 billion), Flight Centre Travel Group (€7.7 billion) which owns FCM Travel in France and CTM (€6 billion) according to EPSA’s ranking.


New Acquisitions in the Pipeline?

The giant born from the merger of Amex GBT and CWT can, however, be seen as both a threat and a new opportunity, with some companies wary of such a supplier or the merger of the two.

“After a year of observation, we are being approached for tenders by multinationals and CAC 40 companies. And whereas the norm used to be three-year contracts, there is a new trend toward longer contracts, from 3 to 5 years,” comments Christophe Hamonic, CEO of FCM Travel France (€240 million in business volume for 2025/26).

Together, the five leaders nevertheless account for only 5.3% of global corporate travel spend (estimated at €1.6 trillion in 2025), leaving room for fully digital entrants and for new alliances.


Advice, Security, Data Protection…

Thus the Marietton Développement group plans to acquire TMCs abroad by the end of the year, notably in the Netherlands, Italy and Portugal, to strengthen its European presence and better serve its clients.

Also read : Marietton: acquisitions of TMCs expected soon

Because companies demand new commitments and services from TMCs, which require substantial resources. “They want advisory services to better procure and adapt their buying behavior in a context of rising prices” adds Christophe Hamonic.

They also express new expectations, particularly regarding data protection and sovereignty and the geosecurity of employees. “For example, we can identify all employees of a company in a specific area in 15 to 45 minutes, and implement a security plan in 1 hour and 30 minutes,” the CEO completes.


Aviation: Brussels Targets Carbon Quotas, Threatens Prices and European Airlines? [ABO]


ETS : Bruxelles veut étendre les quotas carbone, une menace pour les compagnies européennes ? - Depositphotos.com Auteur symbiot

Hurtigruten


Hard times for the Gulf hubs.

While geopolitical tensions and thus instability persist in the region, affecting air traffic, the appeal of the Gulf’s strongholds— notably the Doha, Dubai, and Abu Dhabi hubs— could further diminish in the years to come.

Indeed, in a proposal for a directive from the European Parliament and the Council, it is learned that the European Commission plans to extend its Emissions Trading System, the ETS, beyond intra-European flights.

Eric Drésin, secretary general of ECTAA (the European association of travel agents and tour operators), told TourMaG that this project is very recent, “we are really at the very beginnings of discussions on these issues. But there could be an increase in costs for the airlines.”

Briefly remind what the ETS are, Emissions Trading Schemes in English, which can be translated as: systems for trading emission rights. A system introduced in 2005 obliging companies to purchase rights to emit CO₂.


Chinese and Americans Spared by Brussels

Regarding air transport, these emission quotas apply only to flights within Europe.

But starting in 2029, Brussels aims to adjust the criteria and include the scheme for flights whose destinations are less than 5,000 kilometers from Frankfurt.

Would then be affected a portion of Africa, of Russia and especially the Middle East with carriers such as Emirates, Qatar, Etihad or even the “little” Riyadh Air. This extension, on the simple principle that the farther you go the more you pay, can be understood. However Brussels is up against the hard law of the strongest which seems to become the law “full stop.” The famous 5,000 kilometers thus completely spare the United States and China, which had suggested that in the event of new “taxes” there would be retaliations.


Carbon quotas: European airlines protest

With this proposed ETS extension, at first glance one might think Brussels is restoring a bit of fairness in the fierce competition between European carriers and those from the Gulf that will now be impacted.

But most major European-based airlines think the opposite. For groups like Air France-KLM, Lufthansa or IAG, this extension would cover hundreds of new routes among those they operate and thus ETS costs would truly explode.

In the columns of the Dutch daily De Volkskrant, the carrier KLM had said that it already pays €172 million for emission rights, i.e., 1.5% of its total costs, and viewed a massive price rise with dismay in the coming years.

By means of a note published last May, Air France-KLM informed Brussels that it opposes “firmly any extension of the EU ETS to all flights departing the European Union to destinations outside Europe.” The group asserts that such a measure would further increase the decarbonization burden already disproportionately borne by European carriers. It adds that it would amplify distortions of competition vis-à-vis non-European carriers and could provoke retaliation measures from third countries.

And this document, produced by Air France-KLM’s top management, goes well beyond a mere protest. It is also a counterproposal to Brussels’ upcoming revision of the European emissions trading system, to which the group says it would contribute more effectively and profitably to the EU’s 2050 climate neutrality goal.

Among the proposed measures, and besides maintaining the current geographic scope of the ETS, Air France-KLM also calls for extending the free carbon quotas granted to carriers using SAF to beyond 2030, a limit set by Brussels.

Known as FEETS (Fuel EU ETS Support), this temporary mechanism allocates free carbon quotas called SAF Allowances to carriers using SAF to reduce their ETS bill.

This transitional measure, designed as an encouragement to adopt SAF, is supposed to end in principle in 2030 but for Air France-KLM, that limit is incompatible with industrial SAF investments that are planned over 15–20 years and with the ramping up of SAF-fuel obligations, which remains for a long time far more expensive than kerosene and will have to be carried in the tanks at 70% by 2050.


Plans to Abandon Routes?

In Air France-KLM’s document, the group also seems ready for significant concessions, notably route abandonments, provided that this SAF Allowances scheme is extended to intermodal practices feeding the group’s hubs at Paris-Charles de Gaulle and Amsterdam-Schiphol.

In other words, if Brussels were to reward airlines with free carbon quotas for transporting passengers by train to their hub, certain routes could simply be dropped.

The group would like to convert air passengers into rail passengers for those connecting to long-haul flights, replacing short- and medium-haul flights that fall under the EU Emissions Trading System.

We are thinking of certain links between French provinces and CDG, or other European cities near Amsterdam such as Brussels.

A little revolution.


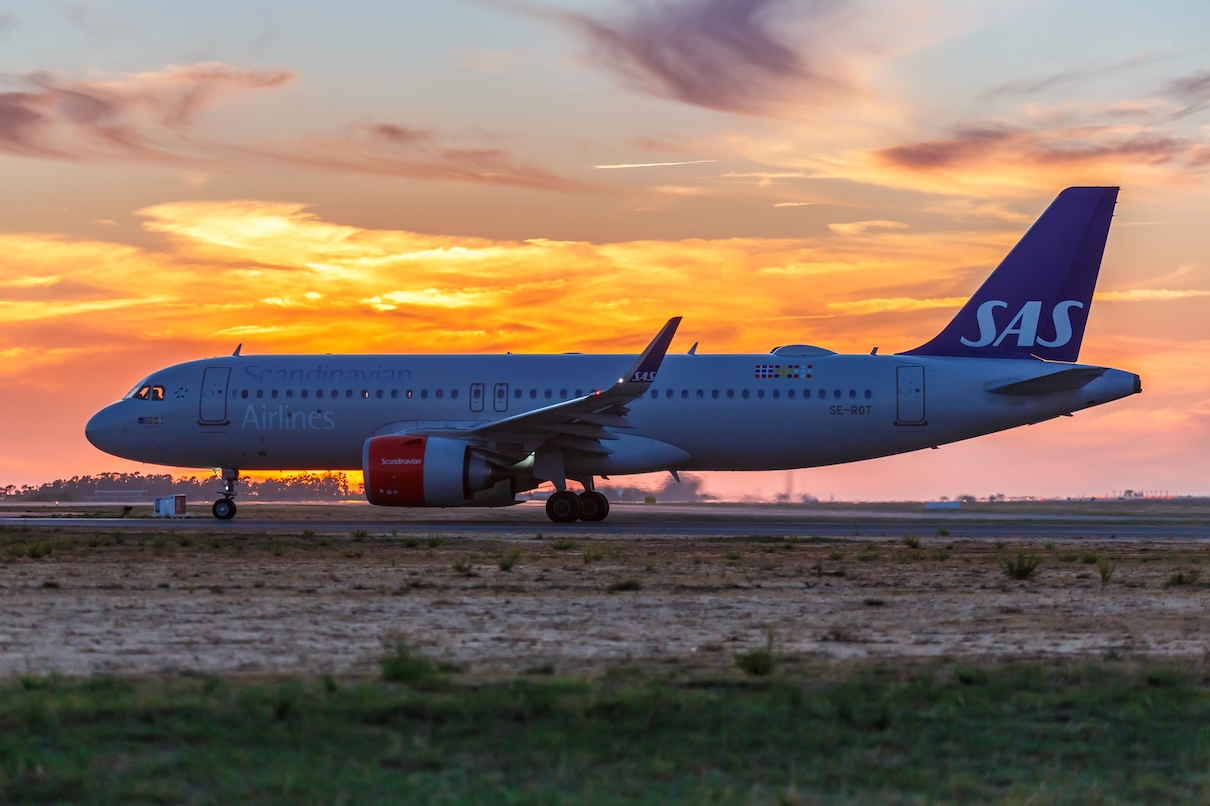
SAS Optimizes Ticket Prices with Amadeus AI


SAS optimise le prix de ses billets grâce à l’IA d’Amadeus - Depositphotos.com, Boarding2Now

Costa Rica


Scandinavian Airlines (SAS) s’appuie désormais sur l’intelligence artificielle pour optimiser la tarification de ses billets.

The airline has rolled out the Amadeus Air Pricing Optimization (AAPO) solution across its entire network.

In markets where the tool is already used via SAS’s website and its NDC distribution channels, Amadeus reports an average revenue uplift for the carrier of more than 3%. The technology provider does not specify the exact scope of markets involved nor the reference period used to measure this progression.

AAPO leverages artificial intelligence as well as real-time data to adjust fares according to demand and market context.

The objective is to enable SAS to gradually move away from a model based on booking classes with predefined fares, in favor of pricing that is more continuous and evolving.


Prices Adjusted More Gradually

For travelers, this evolution should especially make the booking experience more readable, according to Amadeus.

The prices can move more fluidly in response to demand, aiming to limit sharp gaps between different fare classes.

This approach should contribute to strengthening the transparency of the purchasing journey and passengers’ confidence when selecting their ticket.

The solution also enables commercial and revenue-management teams to reduce reliance on manual adjustments. Prices can be continuously modified as demand evolves, within pricing strategies and guardrails defined by the airline.


A Step in the Modernization of Air Distribution

With this deployment, Amadeus also aims to illustrate one of the growing uses of artificial intelligence in the aviation sector: analyzing large volumes of data to automate and refine certain commercial decisions.

The group says it intends to support this evolution within a governance framework anchored notably in its AI Office and through strategic partnerships.

For SAS, the challenge now is to continue integrating these tools into a more flexible distribution strategy while maintaining human oversight over the rules and boundaries that govern pricing.


Amelia Brille Published by Amelia Brille TourMaG.com Editor
See all articles by Amelia Brille

  • picto Linkedin
  • picto email
Add TourMaG to your Google News feed Google Actualités icône  

Why Falling Oil Prices Could Change the Game in the Currency Markets [ABO]


Economic Situation

Pourquoi la baisse du pétrole pourrait changer la donne sur le marché des devises - Depositphotos.com, Auteur yellow_man

CroisiEurope


May will be remembered for an historic move in oil. Brent fell by roughly 19% over the month, dipping back to around $92, marking its worst monthly performance since March 2020.

The engine behind this retreat is diplomatic: Washington and Tehran reportedly reached a preliminary agreement to extend their 60-day ceasefire and reopen the Strait of Hormuz, through which about a fifth of global oil and LNG passes. Tehran would commit to clearing the passage of mines within 30 days. An important caveat: Trump has not yet endorsed the terms, and JD Vance tempered the prevailing optimism. Nothing has been signed.

This pullback changes the inflation equation. Energy had been fueling the price spiral since the outbreak of the conflict at the end of February. If the price of crude stabilizes at a lower level for a sustained period, inflationary pressures should mechanically ease in the coming months.

And yet, the ECB is preparing to tighten on June 11, with a market-implied 90% probability. A 25 basis-point rise would lift the deposit rate from 2.00% to 2.25%, the first tightening since 2023. Why tighten when the energy shock is receding? Because the ECB does not react to yesterday’s oil, but to today’s inflation.

In April, harmonized inflation rose to 3.0% across the euro area, and May flash estimates show a persistent acceleration in France, Italy and Spain. The figures are in, and some governors would have argued for a hike as early as April.

And the euro, meanwhile, remains stuck below 1.17, caught between diplomatic optimism and Frankfurt’s monetary resolve.


Exchange Rates: The Technical View

When oil plunges, safe-haven currencies give up their gains first. The Swiss franc is the clearest example: EUR/CHF has risen to around 0.9105 after peaking near 0.90 during the crisis. The flight-to-safety pressure is easing, and the SNB, with its policy rate at zero, allows it to stand by.

EUR/USD remains stuck around 1.1654, near a six-week low. As long as the Fed keeps its range at 3.50%-3.75% with no hint of easing, the dollar maintains a yield advantage that outstrips every other factor. Technically, the 1.1550-1.1600 area acts as support: below it, the path to 1.1500 opens.

Above this, the 100-day moving average near 1.1720 caps any rebound. EUR/GBP hovers around 0.8650, with no significant underlying movement. EUR/CAD sits near 1.5980: the Canadian dollar is naturally exposed to oil, and a persistently lower oil price would weaken it, thereby mechanically supporting the pair. Finally, EUR/JPY around 185.5 is the issue to watch this week.

The Governor of the Bank of Japan is due to speak soon, and any signal about the continuation of Japan’s monetary normalization could wake a yen that has notably lagged.


WEEKLY SUPPORTS WEEKLY RESISTANCES
S2 S1 R1 R2
EUR/USD 1.1500 1.1580 1.1720 1.1800
EUR/GBP 0.8560 0.8610 0.8700 0.8750
EUR/CHF 0.9020 0.9060 0.9150 0.9200
EUR/CAD 1.5850 1.5920 1.6050 1.6130
EUR/JPY 183.50 184.50 186.50 188.00


The supports and resistances shown below indicate, respectively, the low and high points within which prices are expected to move over the course of the week.


The information presented in this publication is provided for informational purposes only and does not constitute investment advice, an offer to buy or sell, or a solicitation to engage in any investment activity.


Mondial Change is a French financial institution, founded in 2015, specializing in the management of international payments and foreign exchange risk.

Mondial Change also supports many players in the tourism sector: travel agencies, group organizers, tour operators, inbound operators…

www.mondialchange.com

Contact: [email protected]


Costa Guarantees Mediterranean Fuel Prices All Summer


© Costa Croisières

CroisiEurope


Fuel Guarantee: Transparency and Commitment

First differentiating element, and probably the most impactful today in the customer journey: the guarantee of no fuel-related price increase after booking on the maritime portion. In a context where energy fluctuations remain on everyone’s minds, Costa chooses transparency and commitment. Specifically, for Mediterranean departures this summer, the price displayed at the time of booking is final for departures through September 30, 2026. No surcharge will be added as departure approaches. For travel agents, this promise radically changes the commercial dialogue. It immediately removes a frequent objection and builds a climate of trust. The customer knows where they are going, and, most importantly, how much it will cost, with no surprises. In a competitive market, this price stability becomes a strong competitive advantage capable of tipping the decision.


Flexibility: Free Changes Before Departure

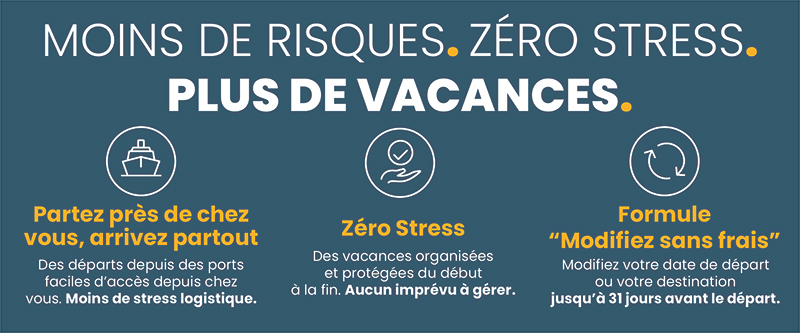
Alongside this price control, there is a direct answer to another key traveler need: flexibility. Costa thus offers free changes up to 31 days before departure. A flexibility that fits perfectly with current expectations, especially among hesitant clients or those planning ahead. Booking no longer means rigid commitment, but securing an opportunity while keeping the ability to adjust the plan. For sellers, this approach greatly facilitates conversion: it helps encourage immediate decision-making by reducing the sense of risk.


Modifiez sans frais © Costa Croisières


“Today, the true value when choosing a vacation lies in the ability to plan it with complete serenity. Travelers who book in advance seek both simple solutions and the freedom to adapt their plans if circumstances evolve. This is what our ‘Modify without fees’ offer makes possible,” says Aurélie SOULAT, France Commercial Director of Costa Croisières. “This flexibility is part of a broader approach of transparency and reassurance, with notably our guarantee of a locked-in price, with no fuel-related increases after booking. In a context where budget control is essential, it is fundamental to be able to offer our clients a clear view of the final price of their holidays, with no surprises.”

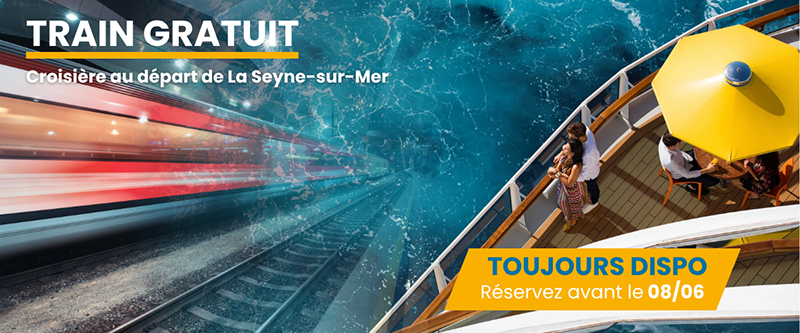
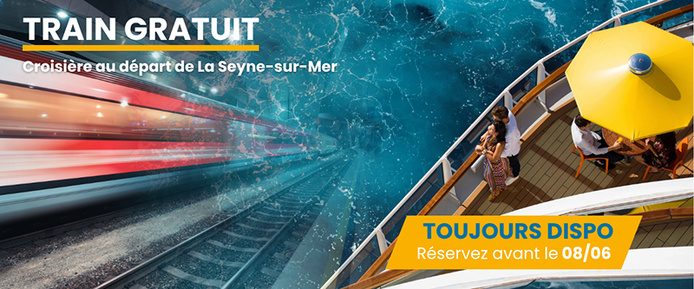
But beyond price and flexibility, Costa also provides a concrete answer to a very operational constraint: access to the departure port. On this point, the cruise line enriches its offering with simple and attractive solutions, notably around the Costa Pacifica. For certain departures from La Seyne-sur-Mer, a free train option is offered from Paris and Lyon. An initiative particularly relevant to broaden the catchment area, attract an urban clientele or meet the expectations of travelers who want to avoid driving. This ease of transportation fits into a seamless customer journey mindset, where every step of the trip is designed to be simple.


Train gratuit au départ de Paris & Lyon © Costa Croisières


Enhanced Accessibility: Train, Car, and Alternatives to Flying

Simultaneously, departures from Marseille also enjoy excellent accessibility. The port is easily reachable by train, with direct connections from many French cities, and also by car, providing great scheduling freedom. This plurality of options lets agents tailor their messaging to the client profiles, highlighting the most relevant solution according to their travel habits.

Ultimately, Costa builds a coherent and especially effective proposition: a secured price, flexible booking, and simplified access. Three elements that directly meet market expectations and give travel agents tangible, immediately actionable arguments at the point of sale. In a context where reassurance has become a key conversion factor, this approach not only facilitates the sale but also positions cruising as a clear, calm, and controlled choice.


A Clear, Readable, and Accessible Pricing Policy

Beyond the fuel guarantee, Costa also strengthens its appeal with a powerful promotional offer: -50% off the second passenger until June 8, 2026.

This promotion helps reposition cruising as a product that is both competitive and transparent. The client perceives real value: a fair and controlled price.

By combining a guaranteed price on the cruise portion, an immediate discount, and flexibility, Costa offers a pricing narrative that is clear, reassuring, and engaging. A strategy that perfectly meets current market expectations and makes the act of purchasing easier than ever.